
 Blue Cloud Movie Ranch Releases Revised Rates and Introduces A New Set
 Federal Film & TV Production Incentive Would Drive Economic and Jobs Boost for U.S.
 Screen the Emmys at the historic Lot at Formosa
 Historic Downtown Theater Now available for Halloween & Emmys Season
 Broadcast Video Auctions
Fall Auction: September 2026 CAP Announced Support for a Federal Incentive
 Onslaught Build with Reel Monster Trucks
 BULLITT NIGHT: Celebrating 58 Years of a Cinematic and Automotive Icon
 Looking for a Helicopter or Aircraft for your next production
 Step and Repeat LA Creates Custom Media Wall for Eli Roth's Ice Cream Man
 WonderWorks To Celebrate 50 Years Of Star Trek
 Cop Shop LA is Celebrating 26 years in business!
 All Creatures Great and Small completes classic Cheetos commercial
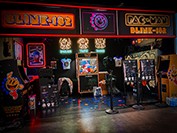 Blink-182 × PAC-MAN Takes Over Comic-Con with a Custom Arcade Experience
 New Portable Cooling Solutions for Your Next Production
 NOW PLAYING: The End of Oak Street
 Rain-Out Protection Reimagined
 Fritz Coleman to Host 13th Annual LMGI Awards Honoring Vince Gilligan, AFCI, EMA and Mike Fantasia
industry news
The Latest Industry News for the Exciting World of Production.
Creative Handbook puts together a bi-monthly newsletter featuring up-to-date information on events, news and industry changes.
Add My Email
Five most common mistakes made by Producers......and how to avoid them!
December 2, 2025
Email This Article |  |

| 
Productions move fast, and insurance often becomes an afterthought-until something goes wrong. These mistakes can lead to costly delays, damaged reputations, and unexpected expenses. Here's why they happen and how to avoid them.
Many production companies assume their gear is adequately insured under a basic policy. Cameras, lenses, lighting, & grip can easily total tens of thousands of dollars. An unexpected theft or accidental damage could lead to insufficient coverage and a costly out-of-pocket expense.
Tip: Keep an updated inventory with accurate replacement values (including sales tax) and schedule periodic reviews with your insurance broker for continued accuracy. Verify if a co-insurance penalty exists and understand its impact in the event of a loss. Confirm the "valuation" that is attached to your property/inland marine policy, which is typically either "Replacement Value" or "Actual Cash Value." Replacement value preferred.
The motivation to secure General Liability is largely centered around compliance. Fulfilling insurance requirements with a rental house, studio, or client, is a function of your role as a creative, but the impact of costly litigation should also be considered as you explore various insurance solutions. Commercial General Liability insures against costly litigation resulting from 3rd party bodily injury and 3rd property damage. Without it, a single mishap-like a light stand falling over and damaging the floor and/or injuring talent-will often result in litigation and reputational harm.
Tip: Secure Commercial General Liability and explore limit options of $1,000,000 occurrence and $2,000,000 occurrence. A Commercial Umbrella should also be considered. The price difference between an annual GL policy and a short-term General Liability is not as significant as one might think! Speak with an insurance specialist that knows your business and can provide you with a thorough walkthrough of your options.
While its common to issue "Additional Insured" certificates to your vendors, subcontractors, and certain crew members, you should be the one collecting them too. If you don't and something goes wrong, you could be held responsible for someone else's mishap.
Tip: Speak with your insurance broker about the different ways you can mitigate the risk over the course of a production. While an additional insured/loss payee COI is a powerful method of risk mitigation, a production services agreement (MSA) with favorable language is equally as effective at keeping you out of the courtroom.
Crew injuries are just as common on small sets as they are on large scale productions. Without Workers' Comp, medical bills and legal claims fall on you. This applies to both W2 and freelance crew members.
Tip: Verify your state's legal definition of an "employee" vs an "independent contractor." Example: California - https://www.dir.ca.gov/dlse/faq_independentcontractor.htm.
Personal auto or homeowner policies rarely cover business activities. Using your own car for gear transport or storing equipment at home without proper coverage leaves you exposed.
Tip: Confirm business-use endorsements or secure separate policies for production needs. Unless you're a hobbyist, it is strongly advised to purchase a Commercial Entertainment insurance policy.
Productions thrive on creativity and efficiency, but overlooking insurance can turn a smooth shoot into a financial nightmare. Before your next project rolls, take the time to review your coverage with a knowledgeable broker. A few minutes now can save you thousands later.
 Reach out to us at [email protected] or 1-800-726-3701 to get a quote, ask a question, or explore how TCP can support your creative business.
Learn more at www.tcpinsurance.com | [email protected]
Undervalued Equipment
Many production companies assume their gear is adequately insured under a basic policy. Cameras, lenses, lighting, & grip can easily total tens of thousands of dollars. An unexpected theft or accidental damage could lead to insufficient coverage and a costly out-of-pocket expense.
Tip: Keep an updated inventory with accurate replacement values (including sales tax) and schedule periodic reviews with your insurance broker for continued accuracy. Verify if a co-insurance penalty exists and understand its impact in the event of a loss. Confirm the "valuation" that is attached to your property/inland marine policy, which is typically either "Replacement Value" or "Actual Cash Value." Replacement value preferred.
Skipping Liability Coverage
The motivation to secure General Liability is largely centered around compliance. Fulfilling insurance requirements with a rental house, studio, or client, is a function of your role as a creative, but the impact of costly litigation should also be considered as you explore various insurance solutions. Commercial General Liability insures against costly litigation resulting from 3rd party bodily injury and 3rd property damage. Without it, a single mishap-like a light stand falling over and damaging the floor and/or injuring talent-will often result in litigation and reputational harm.
Tip: Secure Commercial General Liability and explore limit options of $1,000,000 occurrence and $2,000,000 occurrence. A Commercial Umbrella should also be considered. The price difference between an annual GL policy and a short-term General Liability is not as significant as one might think! Speak with an insurance specialist that knows your business and can provide you with a thorough walkthrough of your options.
Ignoring Certificates of Insurance (COIs)
While its common to issue "Additional Insured" certificates to your vendors, subcontractors, and certain crew members, you should be the one collecting them too. If you don't and something goes wrong, you could be held responsible for someone else's mishap.
Tip: Speak with your insurance broker about the different ways you can mitigate the risk over the course of a production. While an additional insured/loss payee COI is a powerful method of risk mitigation, a production services agreement (MSA) with favorable language is equally as effective at keeping you out of the courtroom.
Overlooking Workers' Compensation
Crew injuries are just as common on small sets as they are on large scale productions. Without Workers' Comp, medical bills and legal claims fall on you. This applies to both W2 and freelance crew members.
Tip: Verify your state's legal definition of an "employee" vs an "independent contractor." Example: California - https://www.dir.ca.gov/dlse/faq_independentcontractor.htm.
Assuming Personal Policies Apply
Personal auto or homeowner policies rarely cover business activities. Using your own car for gear transport or storing equipment at home without proper coverage leaves you exposed.
Tip: Confirm business-use endorsements or secure separate policies for production needs. Unless you're a hobbyist, it is strongly advised to purchase a Commercial Entertainment insurance policy.
Productions thrive on creativity and efficiency, but overlooking insurance can turn a smooth shoot into a financial nightmare. Before your next project rolls, take the time to review your coverage with a knowledgeable broker. A few minutes now can save you thousands later.
TCP Insurance helps productions stay protected and compliant
Reach out to us at [email protected] or 1-800-726-3701 to get a quote, ask a question, or explore how TCP can support your creative business.Learn more at www.tcpinsurance.com | [email protected]
No Comments
Post Comment
Creative Handbook
17631 Ventura Blvd., Ste. 320
Encino, CA 91316